Buying your first home is one of life’s most exciting milestones. But in today’s real estate market, getting your foot in the door can feel like an uphill battle. With property prices holding firm and traditional banks tightening their lending criteria, many first-time buyers find themselves getting a disheartening “no” when they apply for a standard mortgage.
If a major bank has turned you away because of a small deposit, non-traditional employment, or strict borrowing limits, don’t give up just yet.
Related — Outlook Finance Services
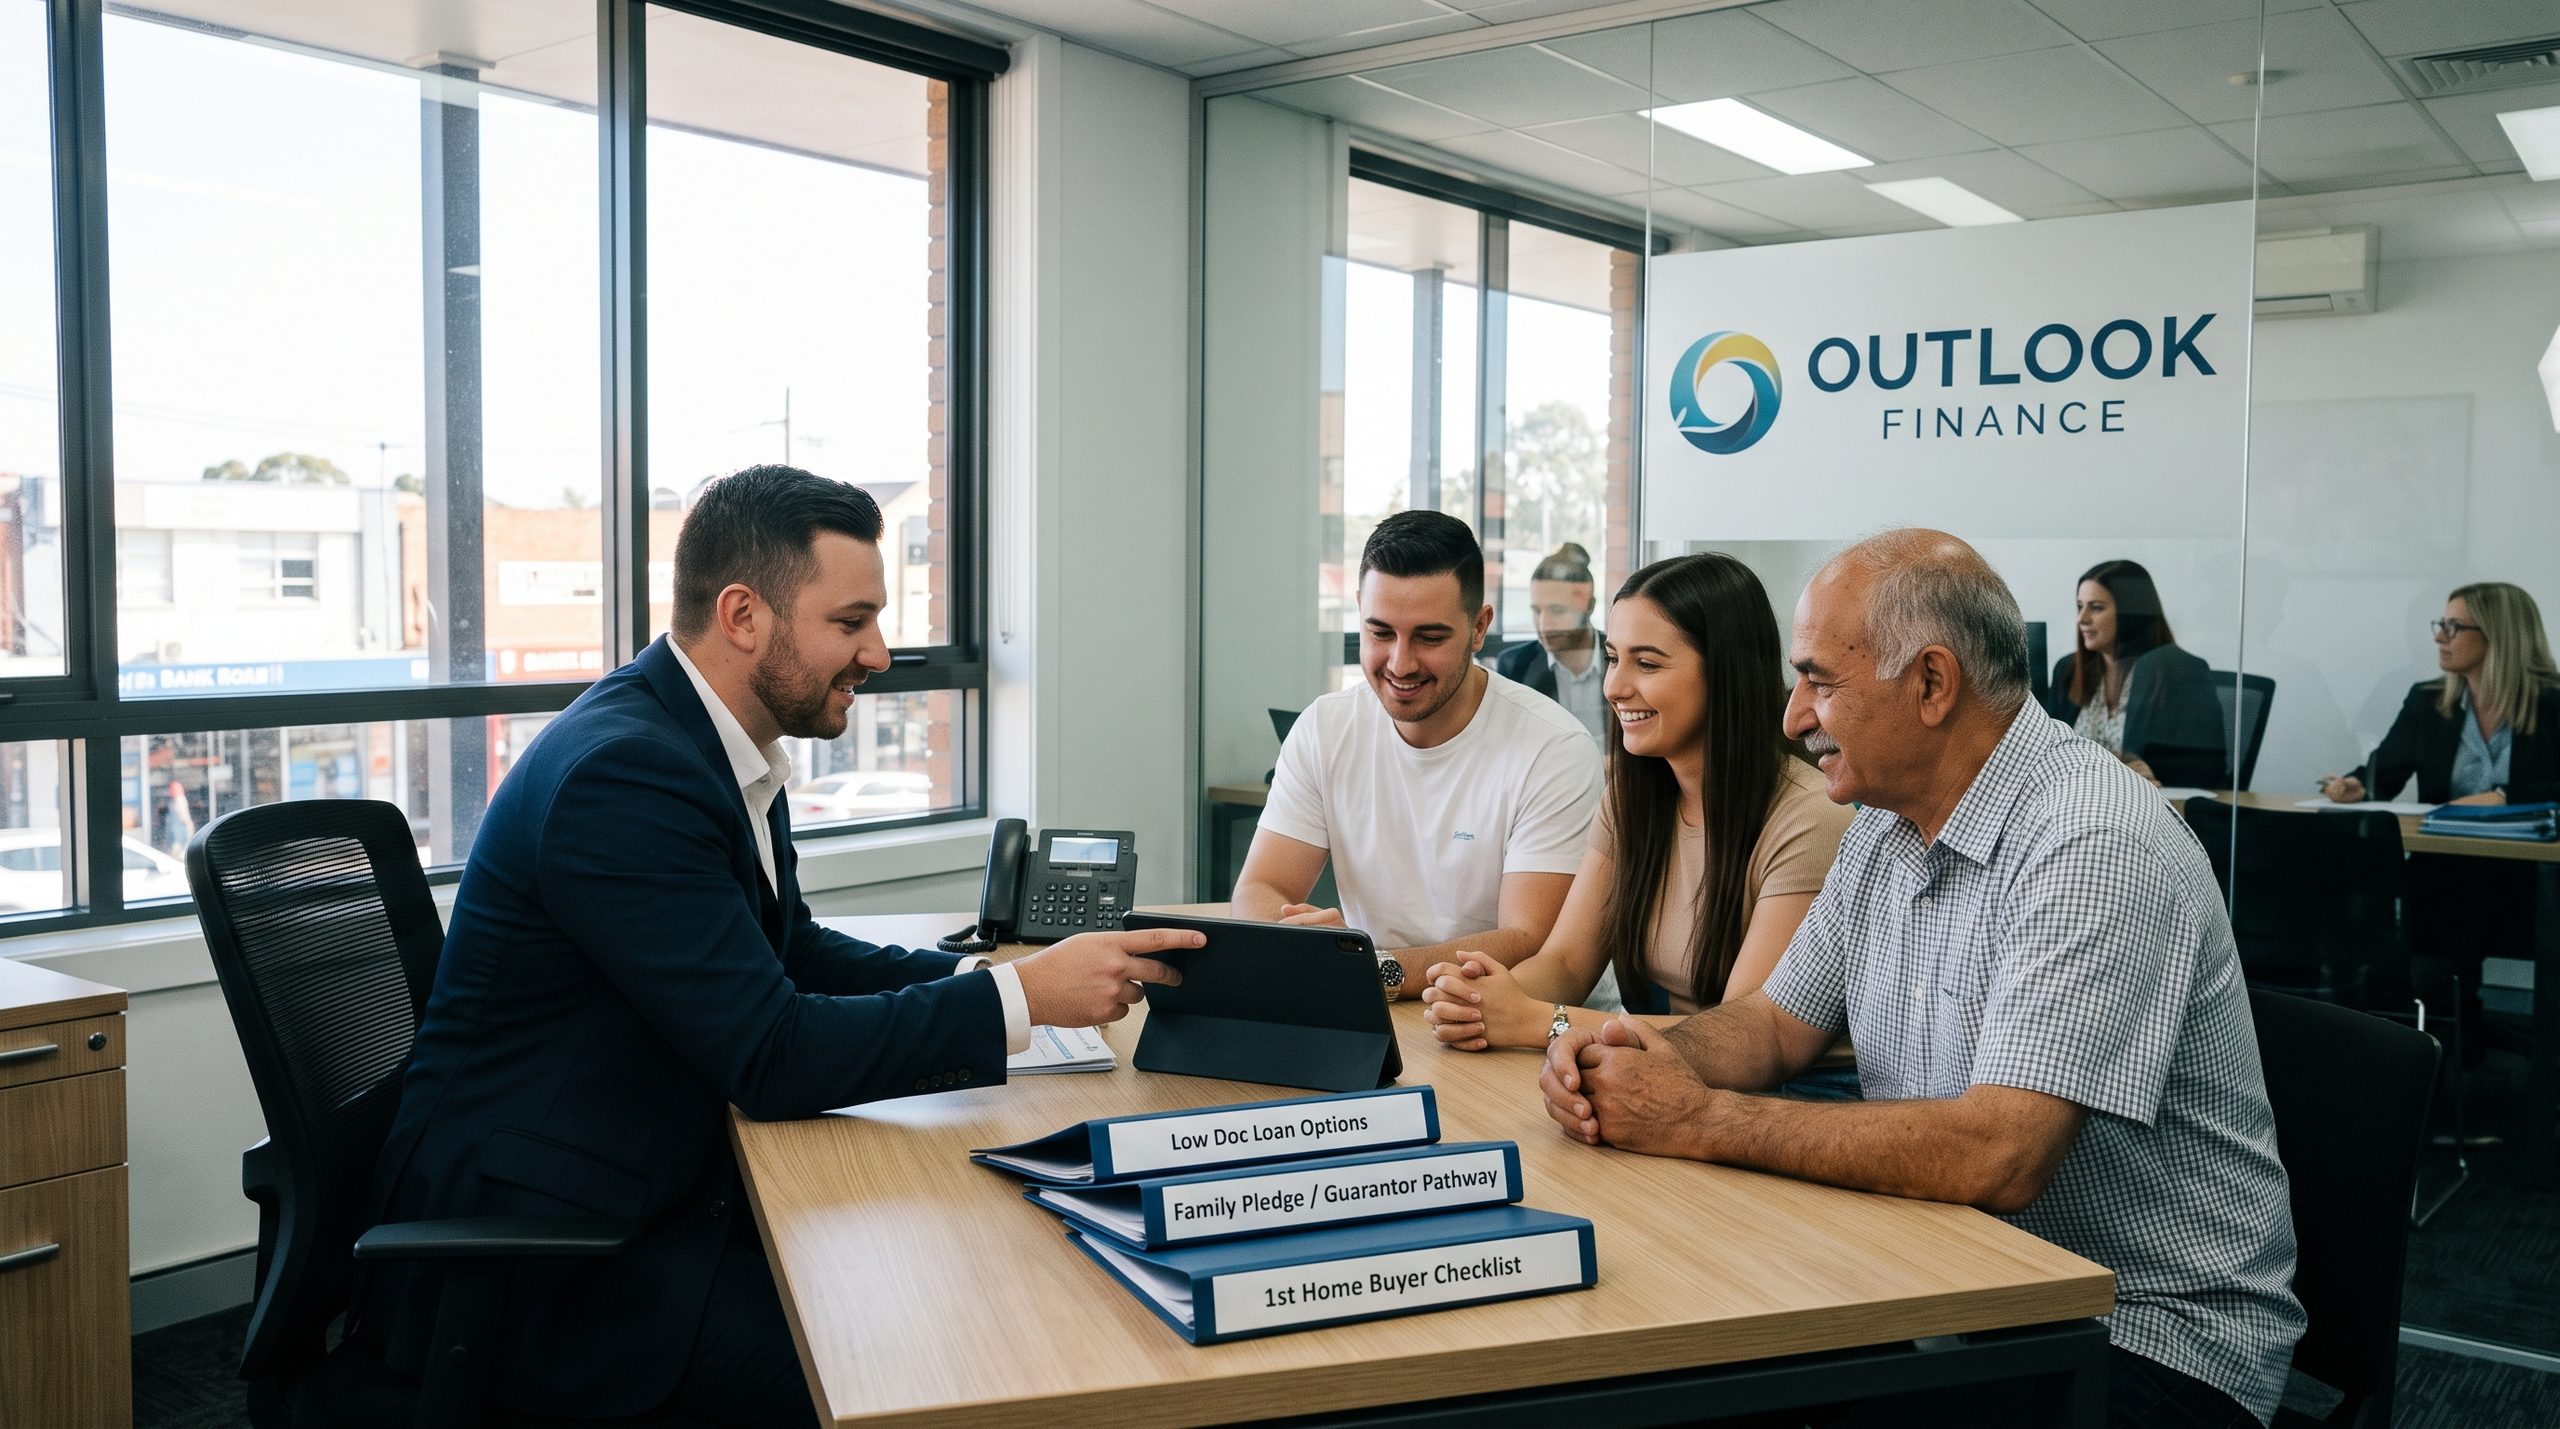
At Outlook Finance, we see first-time buyers overcome these hurdles every day. When traditional lenders close their doors, a range of innovative, alternative lending paths and support schemes can help make your homeownership dreams a reality.
Here is a guide to some of the most effective alternative lending options for first-time buyers.
1. Low Deposit & No-LMI Alternatives
Traditionally, if you don’t have a 20% deposit, you are hit with Lenders Mortgage Insurance (LMI), which can add thousands of dollars to your loan. If you’re struggling to save that 20%, you have other options:
- The Federal Home Guarantee Scheme: Eligible first-time buyers can purchase a home with a deposit as small as 5% without paying LMI. The government guarantees the remaining 15% to the lender.
- Specialist 85% LVR No-LMI Loans: Some non-traditional lenders offer “no-LMI” loans for up to 85% of the property value, helping you keep more cash in your pocket for moving costs and renovations.
2. Guarantor Loans (Using Family Equity)
If you don’t have a large deposit but have family members who own property, a Guarantor Loan can be a game-changer.
- How it works: A family member (usually a parent) offers a portion of the equity in their own home as additional security for your loan.
- The benefit: This can allow you to borrow up to 100% of the purchase price plus costs, completely bypassing the need for a massive deposit or LMI. Over time, as your property’s value grows and you pay down the principal, the guarantee can be removed, releasing your family member from the loan.
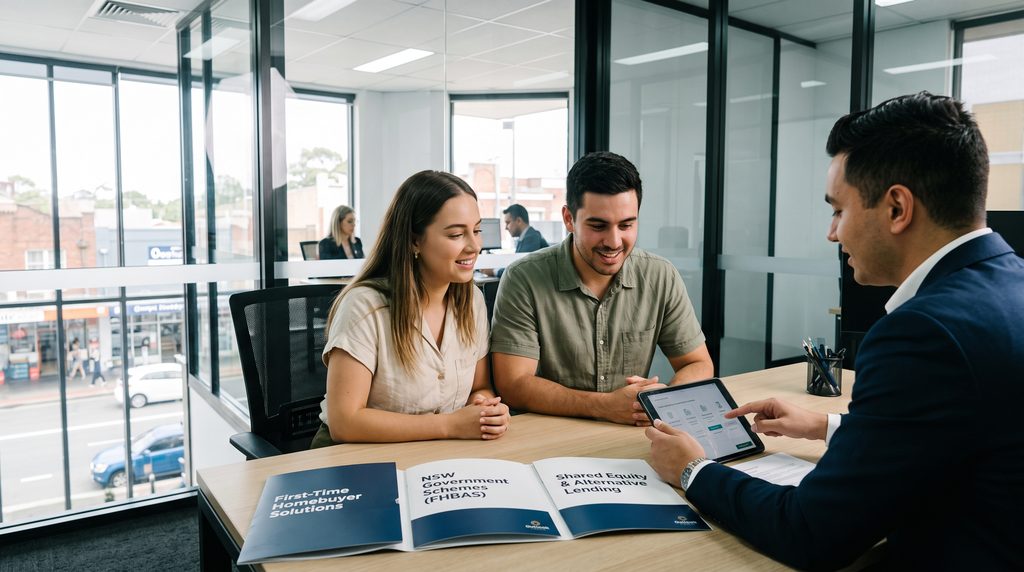
3. NSW First Home Buyers Assistance Scheme (FHBAS)
State-level incentives can also help ease the financial burden. In New South Wales, the First Home Buyers Assistance Scheme (FHBAS) provides significant relief:
- Existing & New Homes: Eligible first-time buyers who purchase a home for $800,000 or less are completely exempt from paying transfer (stamp) duty. Concessions (discounted rates) are also available for properties valued between $800,000 and $1 million.
- $10,000 New Homes Grant: If you choose to build a new home or purchase a brand-new property, you may also qualify for a $10,000 First Home Owner Grant to help top up your funds.
By combining these grants with the right specialist lending product, you can significantly reduce the upfront cash required to buy.
4. Shared Equity Schemes
Shared equity is a highly innovative pathway where a partner—such as the government or a specialized provider—co-invests in the property with you.
- How it works: The co-investor contributes a percentage of the purchase price in exchange for an equivalent share of equity in your home.
- The benefit: This dramatically reduces your loan size, makes your monthly repayments far more manageable, and requires a much smaller deposit. While you can buy back the shared equity over time, it’s a great way to secure your first home when borrowing limits otherwise hold you back.
5. Alternative & Low-Doc Income Verification
If you’ve recently transitioned to being self-employed, run a small business, or work as a contractor, major banks might reject you simply because you don’t have two years of PAYG tax history.
- What we can do: Instead of standard tax returns, we can look at Alternative Documentation (Alt-Doc) or Low-Doc loans. By using active Business Activity Statements (BAS), bank statements, or an accountant’s letter, we can verify your income and get you approved based on your real cash flow, not outdated tax paperwork.
How Outlook Finance Can Help
Securing your first home requires a partner who looks beyond a basic credit score or check-box application. At Outlook Finance, we specialize in finding tailored, out-of-the-box lending solutions.
We’ll sit down with you to:
- Analyze your true financial position, find usable schemes, and map out a pathway.
- Access a wide panel of major and non-bank lenders who offer flexible, innovative policies.
- Prequalify your application to protect your credit score and save you time.
Whether you need a $400,000 apartment or a high-value property up to $30 million, let us handle the heavy lifting while you focus on finding the right keys.
Ready to Unlock Your First Home?
Don’t let a bank’s “no” be the end of your homeownership journey. Let’s explore your alternative pathways together.
Reach out to our Bankstown-based team at Outlook Finance for a free, no-obligation assessment today.
📍 Visit Us: Level 2, 300 Chapel Rd, Bankstown NSW 2200
📞 Call Us: 1300 432 961
Disclaimer: The information provided in this article is general in nature and does not constitute personal financial, investment, or taxation advice. Lending criteria, government scheme eligibility, and concessions are subject to change. For specific advice tailored to your financial circumstances, please consult our specialists.
Key Takeaways
- First-time homebuyers often face rejection from banks due to strict lending criteria.
- Alternative lending options are available, such as low deposit loans without Lenders Mortgage Insurance (LMI).
- Guarantor loans allow family members to provide equity for your home loan, bypassing large deposits.
- NSW offers grants like the First Home Buyers Assistance Scheme for eligible buyers.
- Outlook Finance provides tailored lending solutions and guidance for securing a home loan.
Outlook Finance | First-Time Homebuyer FAQs (Innovative & Low Doc Pathways)
Applying for a mortgage can be particularly challenging for first-time buyers who don’t meet traditional banking requirements. To help you understand your options, our Bankstown and Western Sydney clients have compiled this FAQ focusing on the Low Doc (Alternative Documentation) and Family Pledge (Guarantor) pathways.
Low Doc (Alternative Documentation) Loan FAQs
Yes, you can . If you’re a business owner, contractor, or freelancer, major banks might decline your application if you don’t have two years of traditional tax history.
A Low Doc (Low Documentation) or Alt-Doc (Alternative Documentation) loan allows first-time buyers to verify their income using non-traditional paperwork. Instead of years of tax returns, you can provide bank statements, BAS, or an accountant’s letter.
If you don’t have up-to-date tax returns, you can prove your income using alternative methods:
Business Activity Statements (BAS): Your last 6 to 12 months of ATO-lodged BAS.
Business Bank Statements: 3 to 6 months of statements showing consistent business deposits.
Accountant’s Letter (Declaration): A certified letter from your accountant confirming your estimated income and business viability.
ABN and GST Registration: Confirming your business has been active (usually for at least 12 to 24 months).
Before you choose an accountant, verify they are legally registered by checking the Tax Practitioners Board (TPB) Public Register
.
Because Low Doc loans are processed without traditional paperwork, lenders assess them as carrying slightly more risk, which can result in marginally higher interest rates.
However, at Outlook Finance, we work with a wide range of specialized, non-bank lenders who offer highly competitive rates for self-employed buyers, helping you secure rates close to standard options.
Generally, yes. To secure the best rates and avoid Lenders Mortgage Insurance (LMI) on an Alt-Doc or Low Doc loan, lenders typically require a 20% deposit (meaning an 80% LVR).
However, some lenders will consider a smaller deposit if your other financial metrics (such as your credit score and active cash flow) are strong.
A Family Pledge loan allows a family member (usually your parents) to guarantee a portion of your home loan by offering the equity in their own home as additional security.
This is an excellent option for first-time buyers who can afford mortgage repayments but are struggling to save a deposit.
No Deposit Required: You can borrow up to 100% of the purchase price plus costs (like stamp duty and transfer fees), eliminating the need for a massive upfront deposit.
Bypass Lenders Mortgage Insurance (LMI): Because your guarantor’s equity acts as the security, you don’t have to pay LMI, which can save you tens of thousands of dollars.
Access Better Rates: Lenders assess your application based on an 80% LVR (risk level) due to the guarantee, helping you qualify for more competitive interest rates.
Usually, guarantor options are limited to immediate family members (parents, and in some cases, siblings or grandparents). The guarantor must have sufficient equity in an Australian property (either fully owned or with a small, manageable mortgage) and must meet the lender’s criteria for creditworthiness.
No. This is a common misconception. A “Limited Guarantee” allows your family member to guarantee only a specific portion of the loan—typically the difference between your deposit and 20% of the purchase price (around 15% to 20% of the total loan).
Once you have paid down the loan and your property’s value has increased enough to reach 20% equity on your own, you can apply to have the guarantee removed, completely releasing your family member from any liability.
A guarantor is legally responsible for the guaranteed portion of your loan. If you default on your repayments and the property has to be sold, but there is still a shortfall, the lender has the right to recoup that guaranteed amount from your parent’s home equity.
We always recommend (and most lenders require) that your guarantor obtains independent legal and financial advice before signing to ensure they understand their responsibilities.